.png)
A finance manager closes the month at 9 pm with three Excel files open: sales, stock and payroll. The bank balance does not match the cashbook, two invoices have duplicate numbers, and the VAT deadline is close. That is usually the point when a spreadsheet stops serving the enterprise.
Moving to accounting software Zambia should not mean loading old figures into a new system and hoping for better reports. It needs a controlled 30-day migration that protects tax records, produces compliant invoices and gives management figures it can trust.
We use this plan for SMEs that need stronger financial control without interrupting daily trading. It reflects ZRA, NAPSA, PACRA and ZDA requirements current as of October 2026. Your tax adviser should still review your particular registrations, industry rules and historical balances before go-live.
What must be in place before you move
Start with a decision about the purpose of the system. If the only problem is that one director wants prettier reports, do not migrate during a busy month. If your team cannot reconcile the bank, track customer balances or issue ZRA-compliant invoices consistently, migration deserves priority.
For VAT-registered businesses, Smart Invoice compatibility is not optional. ZRA required VAT taxpayers to register for and use Smart Invoice by 30 September 2024, and standard penalties applied from 1 October 2024. A package that prints an invoice but cannot integrate through a ZRA-certified invoicing system and the Virtual Sales Data Controller does not meet the requirement.
Check the ZRA Smart Invoice taxpayer portal during software selection. Use ZRA’s approved-vendor list to confirm the provider and integration, rather than relying on a sales demonstration. ZRA released additional desktop, online, stock-management and troubleshooting tutorials in July 2026, which can help a finance team test the workflow before committing.
Your new system also needs a calendar that reflects Zambia’s filing dates:
● PAYE through ITF/P16 is due by the 10th of the following month. This deadline matters because payroll tax errors accumulate employee by employee.
● NAPSA monthly returns and payment are due by the 10th of the following month. The same date creates an opportunity to make payroll review one controlled monthly process.
● Turnover Tax return and payment are due by the 14th. A system should identify the relevant sales base without reconstructing it from invoices.
● Electronic VAT return and payment are due by the 18th. A clean sales and purchase ledger makes this review more defensible.
● Annual income-tax return and payment are due by 21 June. Management accounts should reduce the year-end clean-up work, not create it.
For 2026, Turnover Tax has a K2,500 monthly or K30,000 annual exemption. Turnover above that exemption up to K5,000,000 attracts tax at 5 percent. VAT registration remains required when taxable turnover exceeds K800,000, so do not confuse the K5,000,000 Turnover Tax ceiling with the VAT threshold.
Days 1–5: Audit the Excel records and registrations
Begin with an inventory of every workbook that drives a financial decision. Include sales invoices, supplier bills, petty cash, stock cards, debtors, creditors, payroll, fixed assets and bank reconciliations. Ask who updates each file, when they update it and which number management treats as final.
Then check the enterprise records behind the spreadsheets. Confirm the TPIN, registered tax types, ZRA Smart Invoice status, bank accounts, customer and supplier lists, payroll records and the current chart of accounts. A migration cannot correct a registration gap by itself.
Keep the old files and source documents. ZRA requires sales records, invoices, receipts, bank statements and accounts to remain available for at least six years. Preserve read-only Excel copies, scan paper documents where necessary, and decide where the business will store them with access controls.
The most common early mistake is to call the Excel opening balance “the truth” because it has been used for years. Reconcile it first. Match the cashbook to bank statements, customer balances to invoices, supplier balances to bills, stock sheets to a physical count and payroll totals to payment records.
Worked example: A Lusaka wholesaler with scattered stock records
Take a wholesaler with 14 staff, K1.2 million in annual taxable turnover and three warehouses. Its bookkeeper maintained sales in one workbook and stock movements in separate warehouse files. The owners planned to import everything on day one, including item codes that had not been used since 2023.
The finance lead first counted the 80 highest-value stock lines and reconciled them to supplier invoices and physical quantities. The exercise exposed K46,000 in duplicate and obsolete stock records, which the owners reviewed before the import. They set an illustrative internal migration budget of K15,000 for setup, training and data work, and would have spent more correcting errors after go-live.
The judgement call was simple: they did not import every historical line. They kept the old files as retained records and imported clean opening balances, active items and open transactions. That reduced clutter while preserving the six-year ZRA record trail.
Days 6–12: Select the system and map how money moves
Choose software based on the work your people do every day. A trading business needs stock, purchase orders, customer credit controls and Smart Invoice integration. A professional services firm may place greater weight on project billing, debtor follow-up and approval workflows.
Do not choose a package only because it has a low monthly subscription. Test a real Zambian invoice, a credit note, a supplier bill, a bank payment, a payroll journal and a month-end report. The operator should show how each transaction reaches the general ledger and how a user corrects an error without deleting the audit trail.
Map the chart of accounts before configuration. Separate sales types, direct costs, payroll costs, statutory liabilities, bank charges, shareholder balances and inventory movements where those distinctions affect decisions or compliance. A vague account called “expenses” saves time on day one and creates weak management reporting every month after that.
Set user permissions by role. A cashier may create a receipt but should not approve their own refund. A director may approve payments without changing posted transactions. These controls matter because cloud access improves availability, but it also increases the need for clear responsibility.
Build your compliance settings at this stage. Configure VAT where applicable, tax codes, invoice numbering, credit notes, supplier fields and the reporting calendar. For payroll, configure NAPSA at 10 percent of gross earnings, split equally between employer and employee, subject to the 2026 gross-earnings ceiling of K28,920.30 and maximum monthly contribution of K2,892.03.
Do not set NAPSA on basic pay merely because that figure sits at the top of an employment contract. NAPSA applies to gross earnings within the stated ceiling, and the payroll team needs the monthly employee-return fields to support its filing.
Days 13–19: Clean data and import opening balances
Create one approved customer list and one approved supplier list. Remove duplicates, close inactive accounts, standardise names and confirm TPIN or other tax information where your process requires it. A clean master list prevents the same customer appearing under three spellings in the debtors report.
Import only verified opening balances. Your opening trial balance must agree to the final reconciled Excel trial balance for the chosen cut-off date. Keep a signed reconciliation pack that shows how you reached each bank, stock, debtor, creditor and payroll figure.
Test the import in a non-live environment where the provider supports it. Check whether customer balances age correctly, stock quantities and values agree to the count, VAT codes appear correctly, and historical invoice references remain searchable. If the system cannot produce a usable audit trail, pause before putting more data into it.
Cloud backup, permission controls, audit trails and scanned-source-document storage belong in the migration scope. They are not technology extras. They protect the records that ZRA may require for the six-year retention period.
Worked example: An illustrative Kitwe services business
Consider a services business with 12 staff and a K40,000 monthly payroll. Its Excel payroll file calculated deductions correctly in most months, but staff changes sat in email threads and the person preparing the payment also amended employee details. The business had no clear evidence of who approved changes.
During migration, the directors assigned one person to maintain employee data and another to approve payroll. They configured a payroll checklist for PAYE and NAPSA review before the 10th of each month, then tested one parallel pay run. The extra approval step added roughly two hours each month, but it gave the directors a clear record of changes and reduced the risk of an unexplained payroll variance.
They also identified that some reports used basic pay while the statutory calculation needed applicable gross earnings. Catching that distinction before live payroll was less costly than correcting returns and employee records later.
Days 20–25: Run Excel and the new system in parallel
Operate both systems for one reporting cycle. Enter the same sales, purchases, receipts, payments and payroll journals in each system, then compare outputs. This is the stage that shows whether the new process works under real trading conditions.
Reconcile the bank daily during the parallel run. Review aged debtors, aged creditors, inventory, VAT figures and payroll liabilities at least weekly. Investigate differences immediately, because a K500 timing error is easier to resolve than a month of unexplained postings.
Issue test Smart Invoice transactions through the approved process before relying on the system for customer invoices. Confirm that invoice numbers, customer details, tax treatment and credit-note handling work as expected. A generic invoice template is not evidence of ZRA integration.
Keep PACRA outside the accounting-software promise. The system may remind you of deadlines, but it does not file a company annual return or verify beneficial ownership information for you. Companies must submit annual returns to PACRA within three months of their financial year-end, and non-filing can lead to strike-off.
Days 26–30: Go live, reconcile and set ownership
Set a firm cut-off date. Post all remaining Excel items to the agreed date, lock the old operational files and make the new system the single source for day-to-day transactions. Keep retained Excel records accessible, but do not allow parallel posting to continue indefinitely.
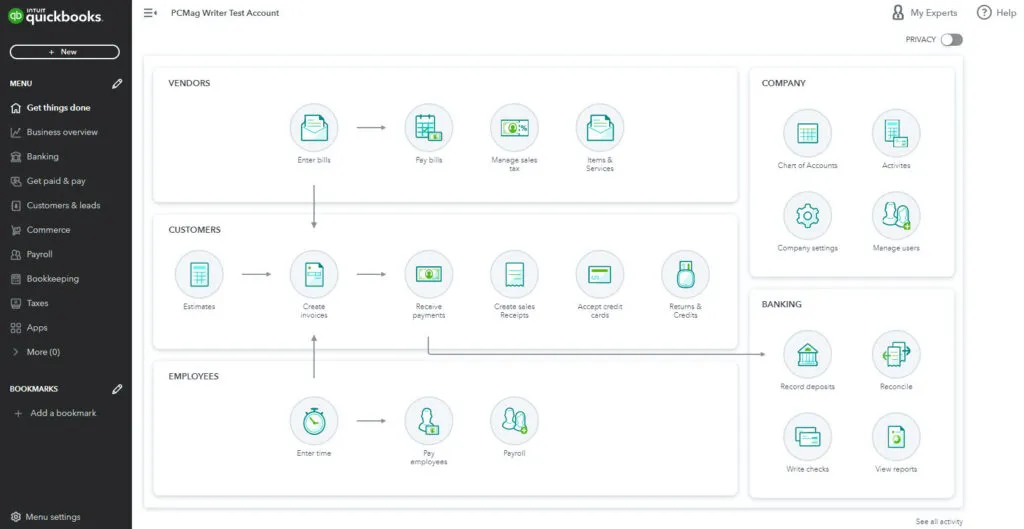
On go-live day, reconcile the bank, debtors, creditors, inventory and payroll once more. Issue the first compliant invoices and confirm that the finance lead can produce a trial balance, profit and loss report, balance sheet, cash position and aged receivables report without rebuilding them manually.
Assign ownership after go-live. Name the person responsible for bank reconciliation, the person approving supplier payments, the person reviewing tax deadlines and the director who receives the monthly management pack. Software creates better visibility only when people act on it.
If the business is formalising or preparing for growth finance, keep the records organised. ZDA business-development support for formalised micro and small enterprises requires PACRA registration, ZRA tax clearance, an MSME application, owners’ NRCs and a business plan. Accurate accounts support the tax clearance and business-plan work, but they do not replace those requirements.
Frequently Asked Questions
Can we move from Excel in 30 days?
Yes, when records are reasonably current and the business limits the first import to verified opening balances, active master data and open transactions. If bank, stock or payroll records have not been reconciled for several months, allow more time because importing unreliable numbers only relocates the problem.
Does every Zambian SME need Smart Invoice integration?
VAT taxpayers need to use Smart Invoice, and businesses using accounting packages or ERPs need ZRA-certified invoicing-system integration through the Virtual Sales Data Controller. Confirm your tax position and provider approval through the ZRA Smart Invoice taxpayer portal before purchase.
Should we delete Excel files after migration?
No. Retain sales records, invoices, receipts, bank statements and accounts for at least six years under ZRA recordkeeping requirements. Lock the final operational files and preserve accessible copies with supporting documents.
Can accounting software manage PACRA and NAPSA obligations automatically?
It can support reminders, payroll calculations and management reporting, but responsibility remains with the enterprise. NAPSA returns and payment remain due by the 10th of the following month, while PACRA annual returns fall due within three months of the company financial year-end.
A controlled migration gives owners timely figures, stronger governance and a clearer basis for growth. Visit our accounting software hub to Speak With Our Team about the right implementation plan for your enterprise.